Methodology
The 6% Problem: Why You Can’t Re-Weight Your Way to Your Own View
Oct 6, 2026 · 5 min read
In this article
Ask Moody’s and S&P to rate the same company’s credit and they will almost always agree. Their ratings correlate at 0.92.[2]
Ask six sustainability rating providers to rate the same company and you get a different picture. Across the major providers, the average correlation is 0.54.[1] On governance alone it drops to 0.30.
- 0.92Credit ratings, Moody’s vs S&P
- 0.54Sustainability ratings, six providers
- 0.30Governance alone
The usual explanation is that sustainability is harder to measure than default risk. That is true, but it hides the more useful point. Credit raters are all estimating the same thing. Sustainability raters are each estimating something different, and calling it by the same name.
Where the disagreement comes from
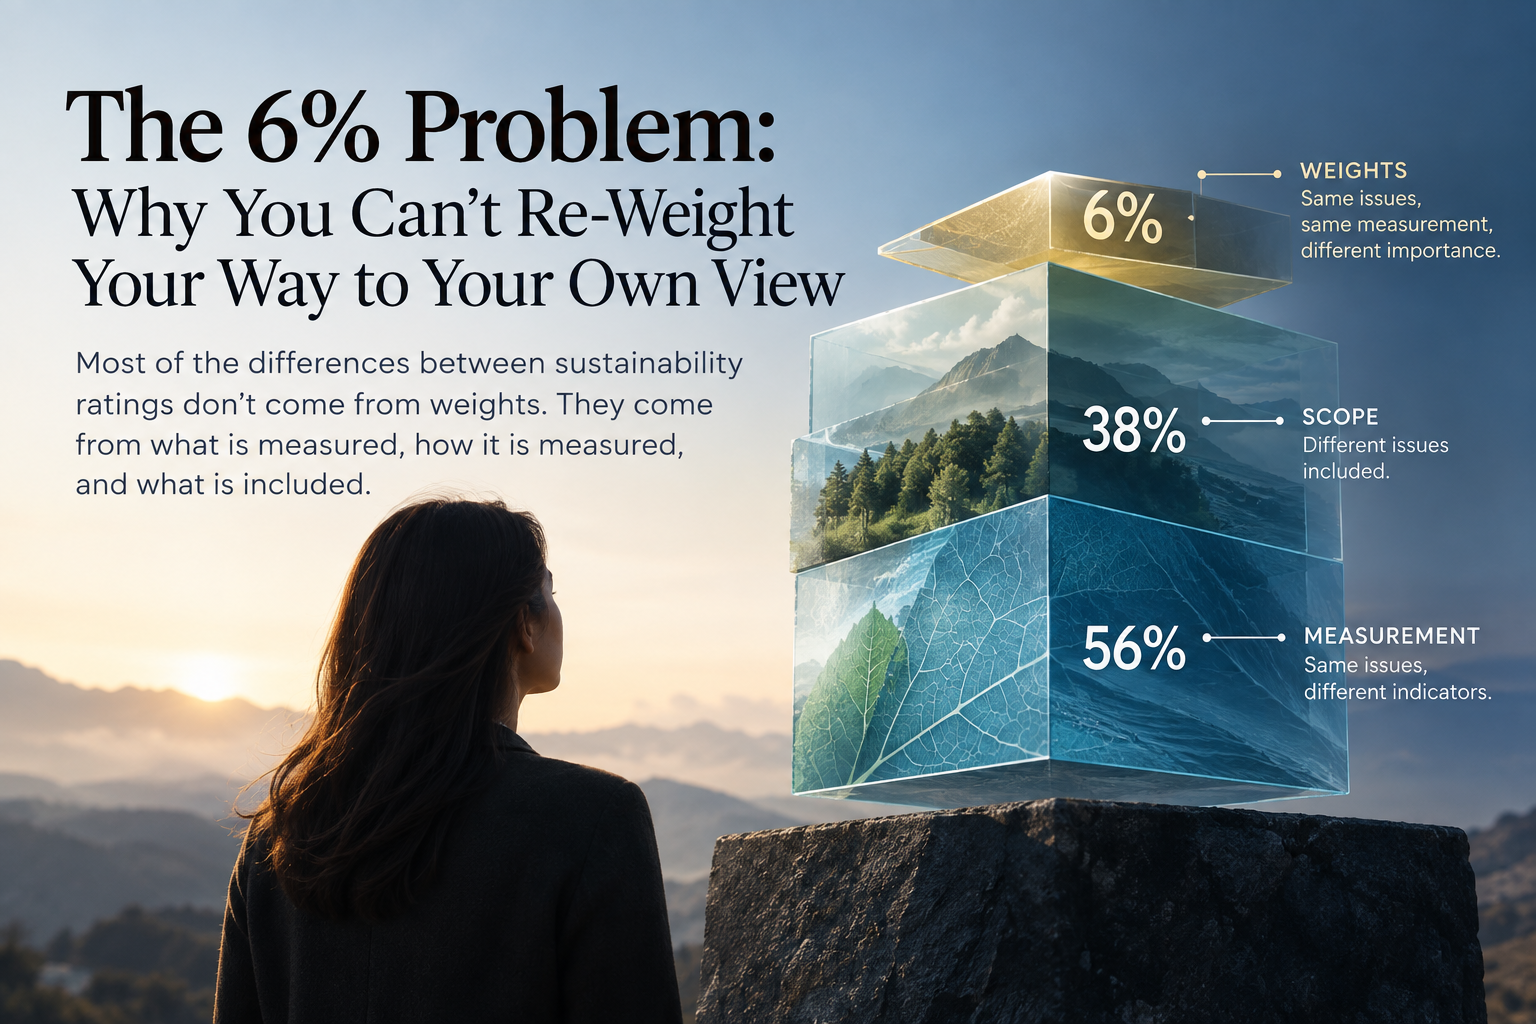
In 2022, Florian Berg, Julian Kölbel and Roberto Rigobon published the study that settled this question.[1] They took ratings for 924 companies from six providers, mapped every underlying indicator to a common set of 64 categories, and worked out why the scores differ. They found three sources of disagreement:[1]
- Measurement56%Two providers look at the same issue, such as labour practices, and measure it with different indicators. One counts policies. Another counts lawsuits.
- Scope38%The providers look at different issues in the first place. One includes lobbying. Another leaves it out.
- Weights6%The providers look at the same issues, measure them the same way, and give them different importance.
That last number matters most to anyone who buys ratings. The common way to make a vendor rating “your own” is to take the pillar scores and re-weight them. More climate, less governance, a tilt toward what your clients care about.
That adjustment works on the 6%. The other 94% stays exactly as the vendor built it.
You have changed the emphasis, but the vendor still decided what to look at and how to measure it.
More disclosure will not fix it
The hopeful view is that this is temporary. Once companies report under common standards, the raters will have the same inputs and their scores will converge.
The evidence points the other way. Christensen, Serafeim and Sikochi (2022)[3] found that when companies disclose more, raters disagree more. The effect holds when disclosure becomes mandatory. It is strongest for outcome measures, the ones investors care about most.
The reason is simple once you see it. Disclosure gives raters more material to interpret, and interpretation is where they differ. A number in a report still needs someone to decide whether it is good, compared with what, and how much it counts.
The accountability now sits with you
For years this was an academic curiosity. It is now a practical problem, because regulators have decided who answers for the number.
The EU regulation on rating providers has applied since 2 July 2026.[4] It supervises the providers, but it deliberately leaves their methodologies alone. And it is explicit that financial institutions bear responsibility when greenwashing accusations are made about their products.
In Canada, the Competition Act still requires adequate and proper substantiation for environmental claims about a business. The UK and other markets are moving the same way.
So picture the investment committee, the client or the supervisor asking why a holding meets your sustainability criteria. “Our vendor scored it BBB” is a thin answer when the method is proprietary and a second vendor scored the same company differently.
Whose judgment is inside the number?
Every rating contains a set of judgments: what matters, how to measure it, and what counts as good. Those judgments cannot be removed. Someone always makes them.
The question for an investor, a bank or a public body is whether those judgments are yours, and whether you can show your work. In practice that means four things:
- You choose the criteria. They follow from your mandate, your view of what is material and what you have promised clients.
- You choose how each one is measured. This is the 56%, and it is the part re-weighting never touches.
- Every score traces back to evidence. A reviewer can go from the number to the page of the document that supports it.
- The method is versioned. You can reproduce the score you relied on two years ago, under the method you used then.
This does not mean throwing vendor ratings away. They are useful inputs and useful benchmarks. When your view differs from the market’s, you want to know, and you want to be able to explain why.
It does mean the decision should rest on a method you own. Many of the largest asset managers have already built one.[5] What has changed is that AI can now read the documents and pull out the evidence at a scale that used to need a large research team. That puts an owned method within reach of institutions that could never have staffed one.
This is the problem we work on at Lucid Axon. Whatever tool you use, the test is the same: for any score you rely on, can you say whose judgment it reflects and where the evidence is? See how it works.
- [1]Berg, Kölbel & Rigobon (2022), Aggregate Confusion: The Divergence of ESG Ratings, Review of Finance 26(6). Source of the 0.54 average correlation and the 56 / 38 / 6 split.
- [2]MIT Sloan, The Aggregate Confusion Project. Source of the 0.92 credit rating comparison.
- [3]Christensen, Serafeim & Sikochi (2022), Why is Corporate Virtue in the Eye of the Beholder? The Case of ESG Ratings, The Accounting Review 97(1).
- [4]Regulation (EU) 2024/3005 on ESG rating activities, Recital 25.
- [5]SquareWell Partners (2021), “The Playing Field”: 30 of the 50 largest asset managers had proprietary ratings.