Stop Renting Your Ratings: Why You Need a Tool to Build Your Own
Nov 2, 2026 · 7 min read
In this article
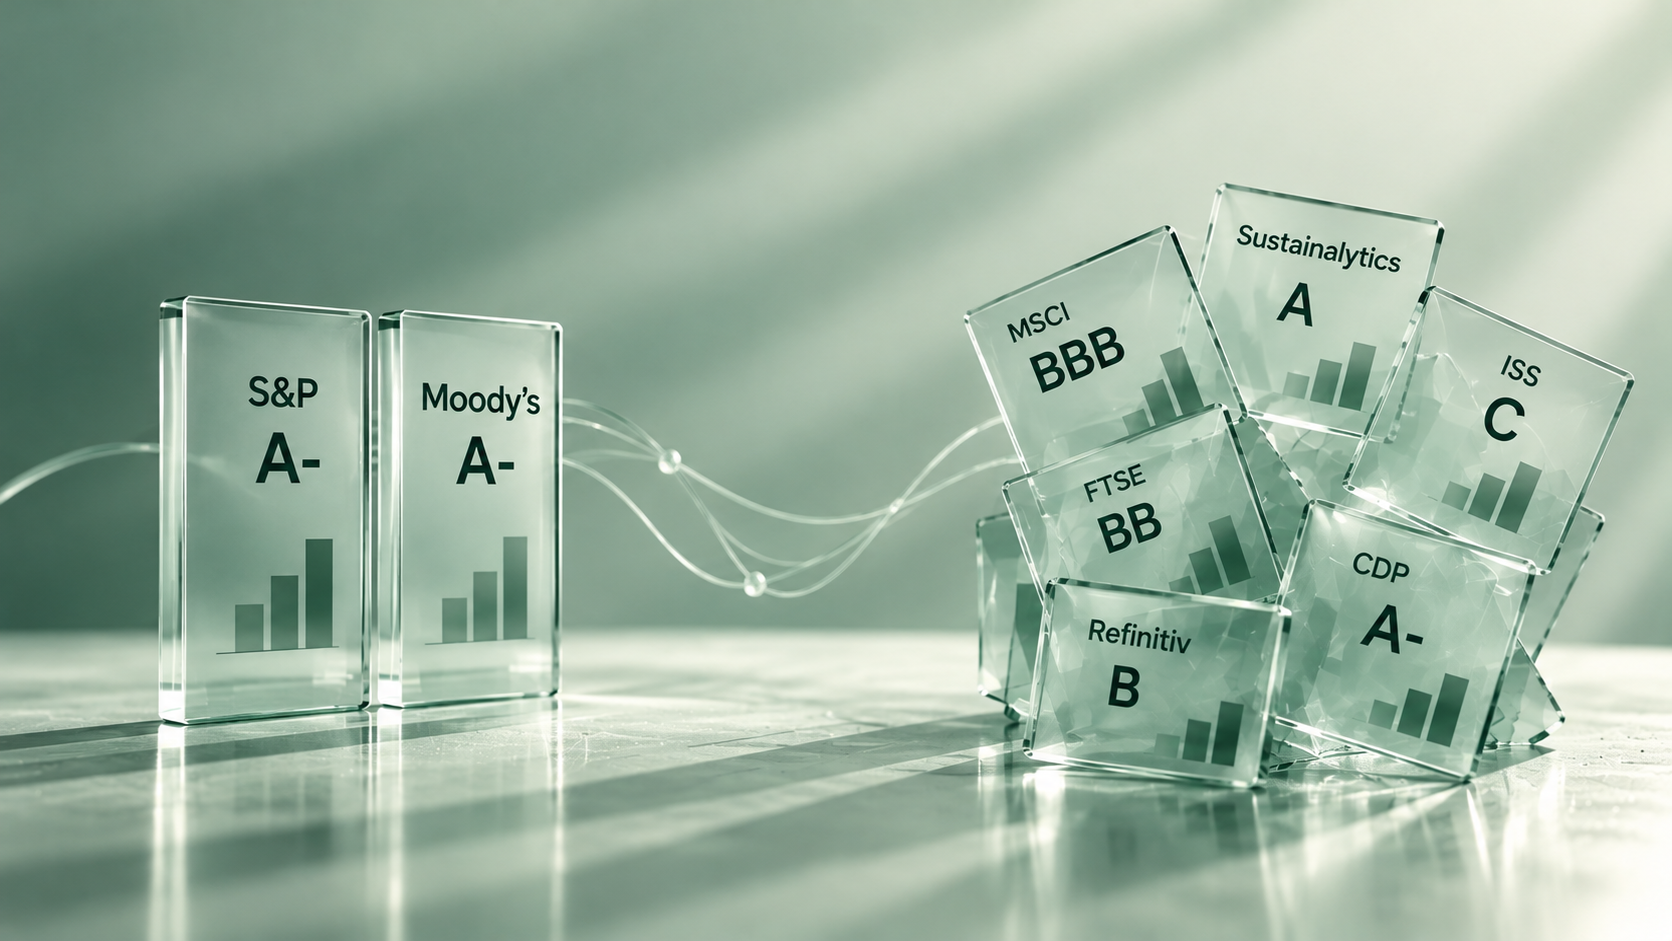
Ask Moody's and S&P to rate the same company's credit and their ratings are highly correlated, at 0.92 [1].
Ask six sustainability rating providers to rate the same company and you get a different picture. Across the major providers, the average correlation is 0.54 [1][2]. On governance alone it drops to 0.30 [2].
- 0.92Correlation between Moody's and S&P credit ratings [1]
- 0.54Average correlation between ESG rating providers [1][2]
- 0.30Average correlation on governance alone [2]
The usual explanation is that sustainability is harder to measure than default risk. That is true, but it hides the more useful point. Credit raters are all estimating the same thing. Sustainability raters are each estimating something different, and calling it by the same name.
Where the disagreement comes from
A 2022 paper in the Review of Finance is the most influential study of this question [2]. It took ratings for 924 companies from six providers, mapped every underlying indicator to a common set of 64 categories, and worked out why the scores differ.
It found three sources of disagreement:
- Measurement56%Two providers look at the same issue, such as labour practices, and measure it with different indicators. One looks at workforce turnover. Another counts labour cases brought against the firm.
- Scope38%The providers look at different issues in the first place. One includes lobbying. Another leaves it out.
- Weights6%The providers look at the same issues, measure them the same way, and give them different importance.
That last number matters most to anyone who buys ratings. The common way to make a vendor rating "your own" is to take the pillar scores and re-weight them. More climate, less governance, a tilt toward what your clients care about.
But in the study, weighting explained only 6% of the disagreement between ratings. Measurement and scope explained the other 94%. Re-weighting will change your score. It does not change what the vendor chose to look at or how the vendor measured it.
Re-weighting will change your score. It does not change what the vendor chose to look at or how the vendor measured it.
More disclosure alone will not fix it
The hopeful view is that common reporting standards will bring ratings closer together by giving providers more comparable inputs.
The evidence is less encouraging. A 2022 study in The Accounting Review found that when companies disclose more, raters disagree more [3]. After countries and stock exchanges made ESG disclosure mandatory, the affected companies disclosed more and raters disagreed more about them. The effect is strongest for outcomes, such as injury rates, rather than for inputs, such as whether a policy exists.
The study's explanation is simple. Disclosure gives raters more material to interpret, and interpretation is where they differ. A number in a report still needs someone to decide whether it is good, compared with what, and how much it counts. Comparable inputs can help, but they do not remove differences in scope, measurement and judgement.
The accountability now sits with you
As sustainability ratings become more embedded in investment decisions, this is no longer just an academic question. Regulators are introducing rules for rating providers and sustainability claims, while institutions still need to explain the judgements behind their own decisions.
The EU regulation on rating providers has applied since 2 July 2026 [4]. It puts providers under supervision and makes them disclose their methods, but it does not set one method that all of them must follow. Recital 25 of the regulation also says that financial institutions should bear responsibility when greenwashing accusations are made about their products [4].
In Canada, the Competition Act still requires adequate and proper substantiation for certain environmental claims about a business. Amendments in March 2026 removed one specific requirement: that the substantiation follow an internationally recognized methodology [5]. The duty to substantiate remains, so the claimant still has to be able to support the claim. In the UK, the FCA's anti-greenwashing rule has required FCA-authorised firms' sustainability claims about their products and services to be fair, clear and not misleading since 31 May 2024 [6].
So picture the investment committee, the client or the supervisor asking why a holding meets your sustainability criteria. "Our vendor scored it BBB" is a thin answer when the method is proprietary and a second vendor scored the same company differently.
Investors are already looking past the score
The market is moving the same way. A 2026 survey of 53 investment professionals, whose organisations manage around $23.5 trillion, repeated questions first asked in 2023, when 33 investors answered [7]. Side by side, the two surveys show how the view of ratings has changed:
| Measure | 2023 | 2026 |
|---|---|---|
| Average trust in ESG ratings (out of 5) | 3.31 | 3.05 |
| Investors naming ratings among their most useful information sources | 53% | 31% |
| Investors using ratings at least weekly | 69% | 58% |
| Investors rating disclosure of a rating's methodology as highly important | 88% | 93% |
Trust is lower, and ratings count for less as a source. Investors now rank their own research first for investment decisions, ahead of direct engagement with companies and ahead of the ratings themselves [7]. What has not faded is the demand for a method that can be inspected. In 2026, 93% rated disclosure of the methodology as highly important and 91% rated its quality as highly important [7].
The samples are small and differ between years, and the survey records what investors say rather than what they do. But the direction fits everything above. Investors are not abandoning ratings. They are treating them as one input to a judgement of their own.
Whose judgement is inside the number?
Every rating contains a set of judgements: what matters, how to measure it, and what counts as good. Those judgements cannot be removed. Someone always makes them.
There are two ways to work with ratings.
Traditional approach: a provider gives you an ESG score.
- The provider defines the indicators.
- The provider defines the weights.
- The provider defines the methodology.
- You consume the score.
Lucid Axon approach: we provide the infrastructure to create your own ESG score.
- You define the indicators and KPIs.
- You select the frameworks and data sources.
- You define the scoring methodology.
- You determine how evidence is evaluated.
- You generate company-level and portfolio-level scores.
- You can update the methodology without rebuilding the entire assessment system.
This distinction is important.
The question for an investor, a bank or a public body is whether those judgements are yours, and whether you can show your work. In practice that means four things:
- You choose the criteria. They follow from your mandate, your view of what is material and what you have promised clients.
- You choose how each one is measured. Measurement was the largest source of disagreement in the study, and re-weighting does not touch it.
- Every score traces back to evidence. A reviewer can go from the number to the page of the document that supports it.
- The method is versioned. You can reproduce the score you relied on two years ago, under the method you used then.
This does not mean throwing vendor ratings away. They are useful inputs and useful benchmarks. When your view differs from the market's, you want to know, and you want to be able to explain why.
It does mean the decision should rest on a method you own. In a 2021 study of the 50 largest asset managers, 30 had already built their own ratings [8]. What has changed is that AI can now help read the documents and pull out the evidence, with people reviewing the results, at a scale that used to need a large research team. That can put an owned method within reach of institutions that could never have staffed one.
This is the problem we work on at Lucid Axon. Whatever tool you use, the test is the same: for any score you rely on, can you say whose judgement it reflects and where the evidence is?
- [1]MIT Sloan, The Aggregate Confusion Project. Source of the 0.54 average correlation and the 0.92 credit rating comparison.
- [2]Aggregate Confusion: The Divergence of ESG Ratings, Review of Finance 26(6), 2022. Source of the 56 / 38 / 6 split and the sample of 924 companies and six providers.
- [3]Why is Corporate Virtue in the Eye of the Beholder? The Case of ESG Ratings, The Accounting Review 97(1), 2022.
- [4]Regulation (EU) 2024/3005 on ESG rating activities, Recitals 25 and 36 and the 2 July 2026 application date.
- [5]Competition Bureau Canada, Environmental claims and greenwashing. Source for the substantiation requirement and the March 2026 amendment.
- [6]Financial Conduct Authority, FG24/3: Finalised guidance on the anti-greenwashing rule. Source for the 31 May 2024 start date.
- [7]ERM Sustainability Institute, Rate the Raters 2026: Beyond the Score, investor survey, October 2026. Source for the sample of 53 investment professionals, the $23.5 trillion in assets, the 2023 and 2026 comparisons, the ranking of information sources and the importance of methodology.
- [8]"The Playing Field", 2021 annual study, as reported by IR Magazine: 30 of the 50 largest asset managers had developed proprietary internal ratings.